Underwritten by: Hong Kong Life Insurance Limited
Insurance Broker Channel Only
GLOBAL strategy timeless LEGACY
In a rapidly changing world, your pace is accelerating too. Whether you are expanding your international horizons, working abroad, pursuing overseas studies, or planning a seamless retirement across borders, we understand your aspirations. Precisely capturing global financial dynamics, we help you adapt flexibly to seize global opportunities and comprehensively plan your wealth legacy.
Wealth Global Multi-Currency Insurance Plan (The "Plan") is a life protection plan designed to support your long-term savings goals while aiming to accumulate your capital with potentially higher returns. The Plan offers flexible features, such as the Change of Policy Currency Option and Policy Split Option, empowering you to navigate financial risks and seize emerging opportunities in global markets. In addition, the Plan is equipped with features including flexible Contingent Policyowner and Life Insured Arrangement, empowering you to architect a comprehensive and sustainable legacy plan.
2 Choices of Premium Payment Terms1 for Selection with Extended Life Protection
The Plan provides 2 choices of Premium Payment Term1, i.e. 2 years1and 5 years1, with extended life protection until age 130 of the Life Insured. If the Policyowner chooses to change the Life Insured2, life protection will be extended to age 130 of the New Life Insured.
Additional Return
The Plan not only provides Guaranteed Cash Value, Annual Dividend (non-guaranteed)3 may also be distributed annually in terms of cash starting from the end of the 2nd Policy Year. You can choose cash withdrawal or leave it within the Policy for interest accumulation3 to meet your personal needs.
In addition, Terminal Dividend (non-guaranteed)3 may be payable at or after the end of the 4th Policy Year when the Policy is fully surrendered by the Policyowner, upon the death of the Life Insured (provided that there is no named and surviving Contingent Life Insured who will become the new Life Insured) or upon Policy Maturity, whichever is earlier.
When the Policy is partially surrendered4 (including partial surrenders4 automatically triggered for the Incapacity Benefit5), Terminal Dividend (non-guaranteed)3 may be payable at or after the end of the 4th Policy Year. The payable amount is equal to the Terminal Dividend (non-guaranteed)3 attributable to the reduced portion of Principal Amount6. Terminal Dividend (non-guaranteed)3 will not accumulate in the Policy.
Flexible Wealth Management to Seize Opportunities Across Global Markets
- Change of Policy Currency Option7
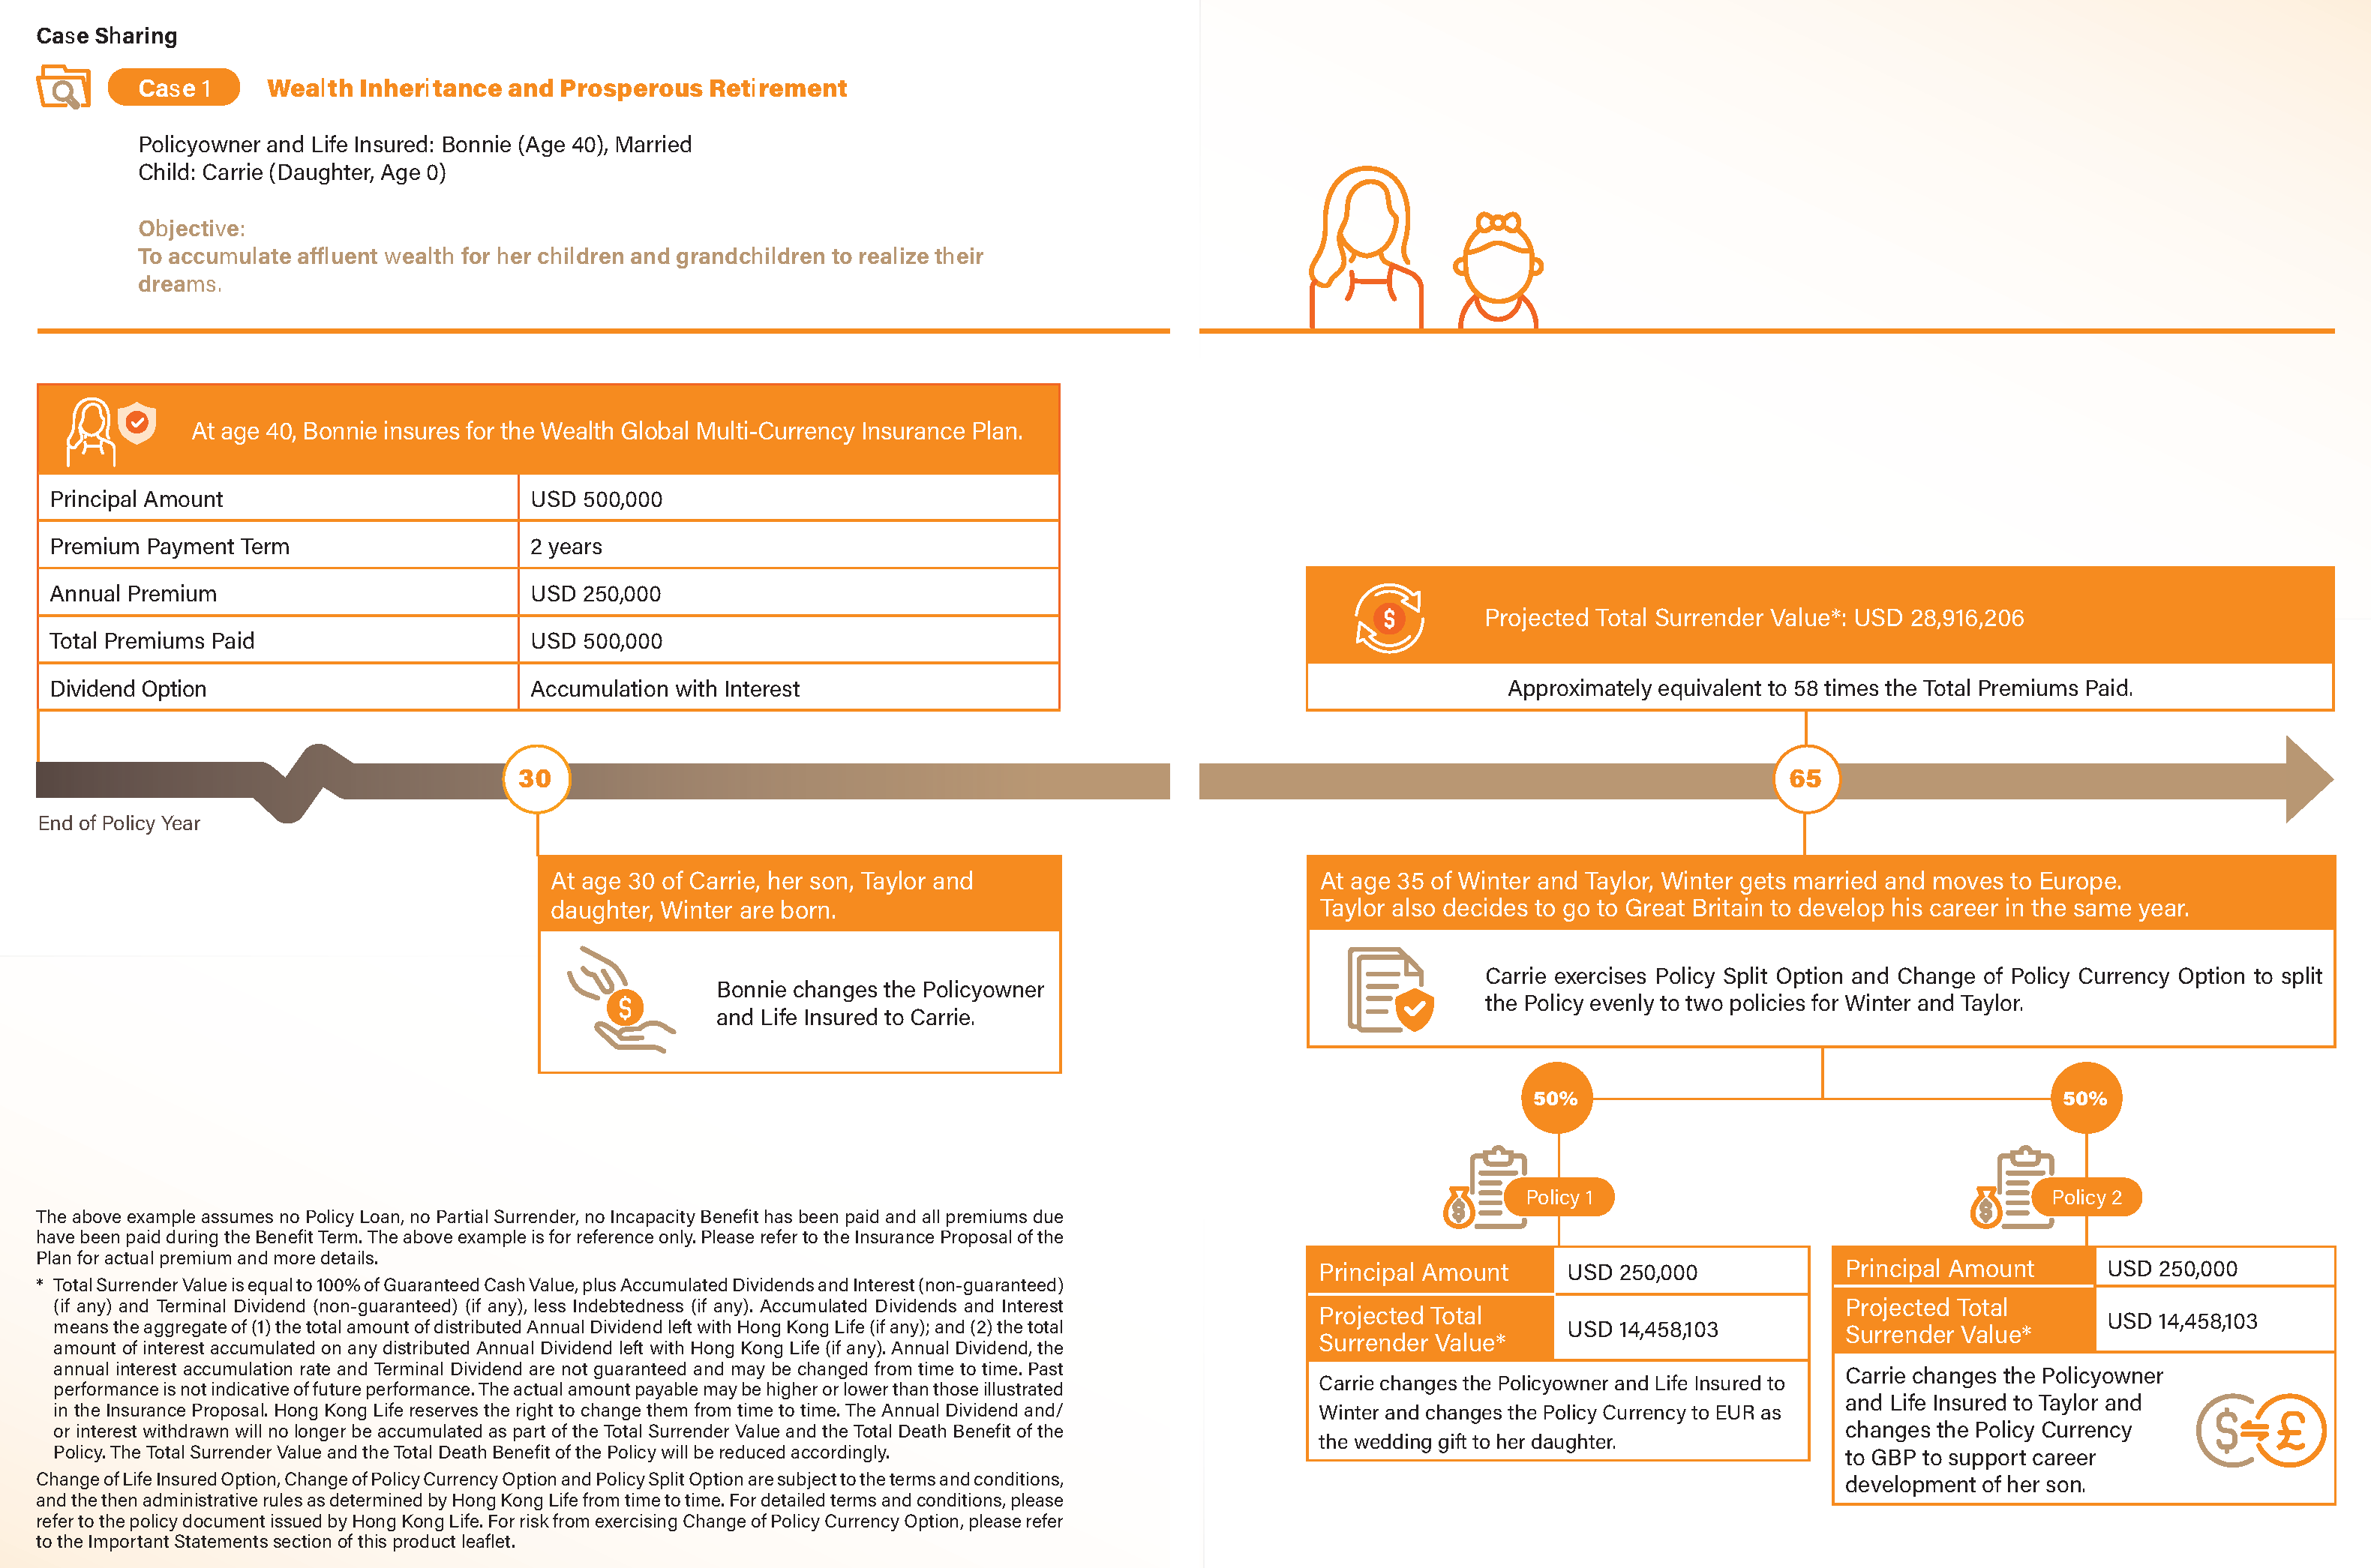
Starting from the 2nd Policy Anniversary (Applicable to 2-Year Premium Payment Term Policies) or the 3rd Policy Anniversary (Applicable to 5-Year Premium Payment Term Policies) while the Plan is in force and the Life Insured is alive, the Policyowner can apply for a change of policy currency7 to change the current Policy Currency of the Policy to a different currency ("New Policy Currency"), such as HKD, USD, RMB, AUD, CAD, EUR, GBP, NZD or SGD (subject to availability as determined by Hong Kong Life at the time of applying the change of policy currency7). This allows you to flexibly allocate your currency mix in line with market trends and to meet your personal needs, enhancing the potential for wealth growth. The Change of Policy Currency Option7 has a maximum limit of 1 time per Policy Year.
- Policy Split Option8
Starting from the 1st Policy Anniversary while the Plan is in force and the Life Insured is alive, the Policyowner can apply for a policy split8 to split the Policy to one separate new policy or multiple separate new policies ("Split Policy(ies)"), by transferring a designated portion of the Principal Amount6 of the Basic Plan of the Policy to each of the Split Policy(ies). This option can be used in conjunction with the Change of Policy Currency Option7 to appropriately address changes in your life planning. It can also be used in conjunction with the Change of Life Insured Option2 to meet your wealth succession arrangement. The Policy Split Option8 may be exercised a maximum of 1 time per Policy Year.
- Withdrawal Arrangement
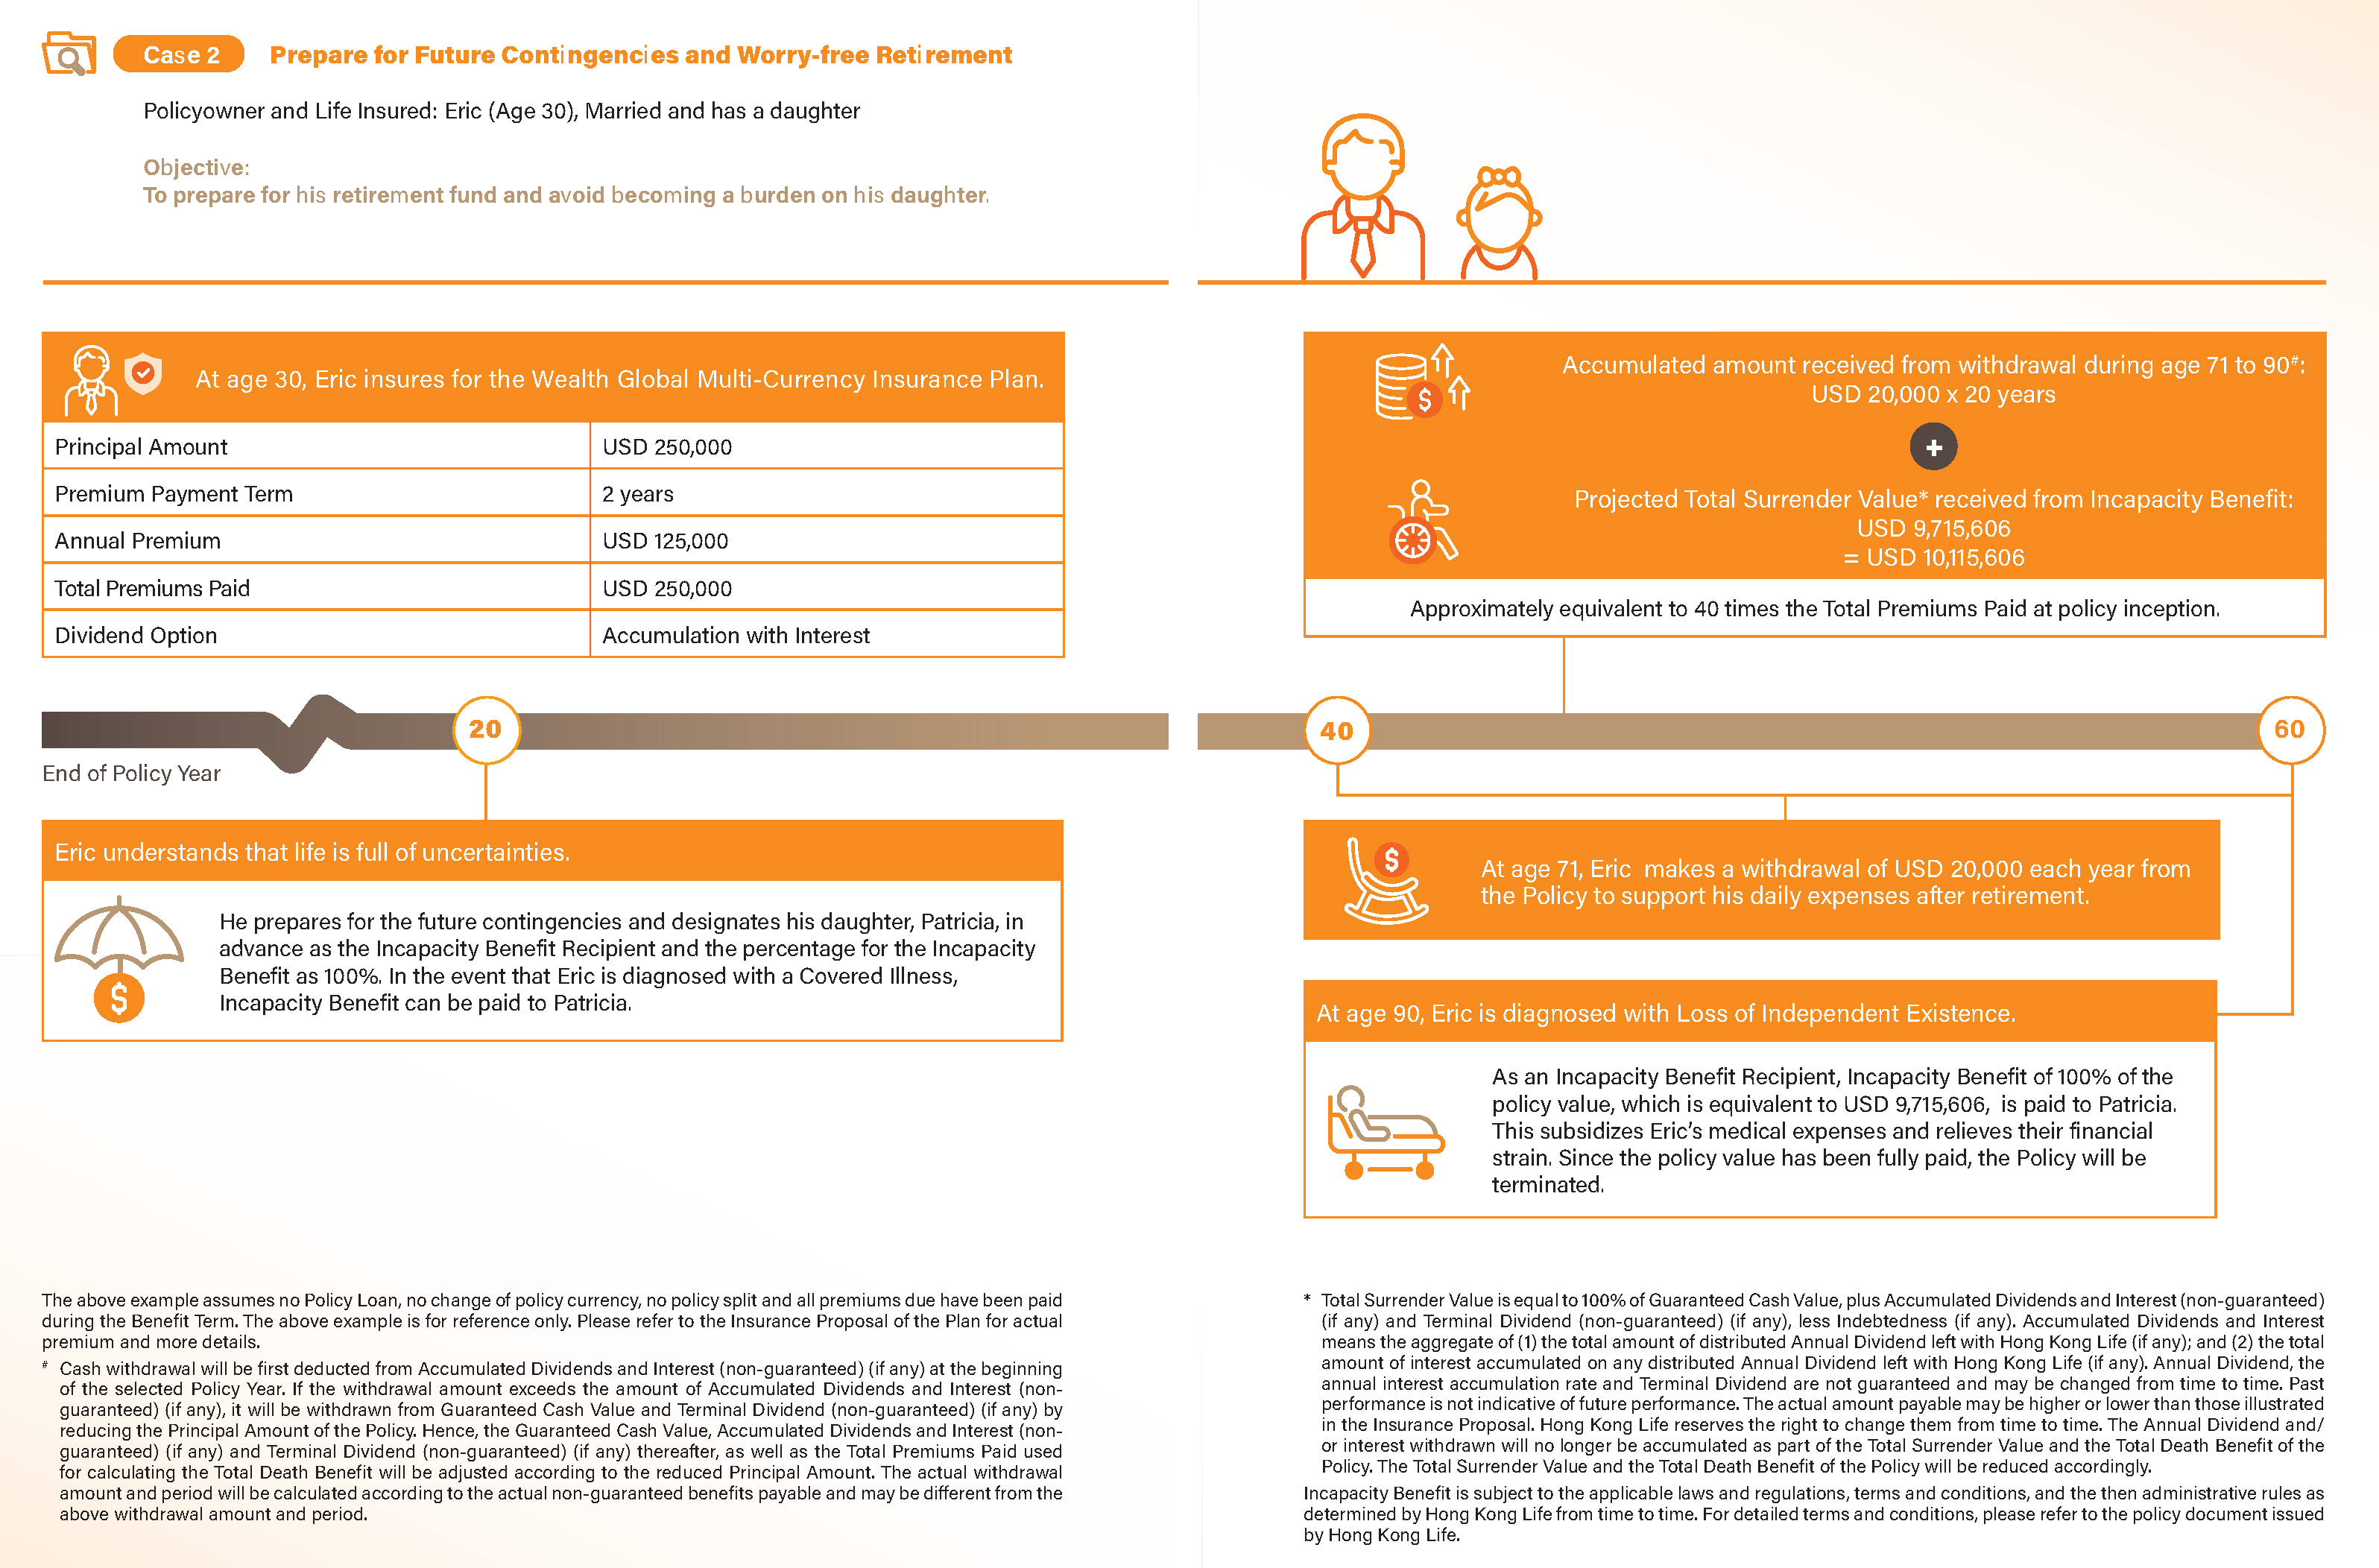
The Policyowner may make a one-off or regular withdrawal from the cash value of the Policy (including the Guaranteed Cash Value (if any), Accumulated Dividends and Interest (non-guaranteed)3,9(if any) and Terminal Dividend (non-guaranteed)3(if any)) according to his/ her needs in order to fulfill the dreams like children's education and fruitful retirement, etc. However, the future cash value of the Policy will be reduced accordingly.
After the Policy has acquired a Guaranteed Cash Value, the Policyowner can opt for Partial Surrender4 after the 1st Policy Anniversary (Applicable to 2-Year Premium Payment Term Policies) / 2nd Policy Anniversary (Applicable to 5-Year Premium Payment Term Policies) to withdraw the Guaranteed Cash Value and Terminal Dividend (non-guaranteed)3(if any) attributable to the reduced portion of Principal Amount6 of the Policy.
Comprehensive Wealth Succession Plan to Cultivate Wealth Across Generations
- Change of Life Insured Option2
While the Plan is in force and the Life Insured is alive, the Policyowner may change the Life Insured2 for an unlimited number of times starting from the 1st Policy Anniversary.
- Contingent Policyowner Arrangement10
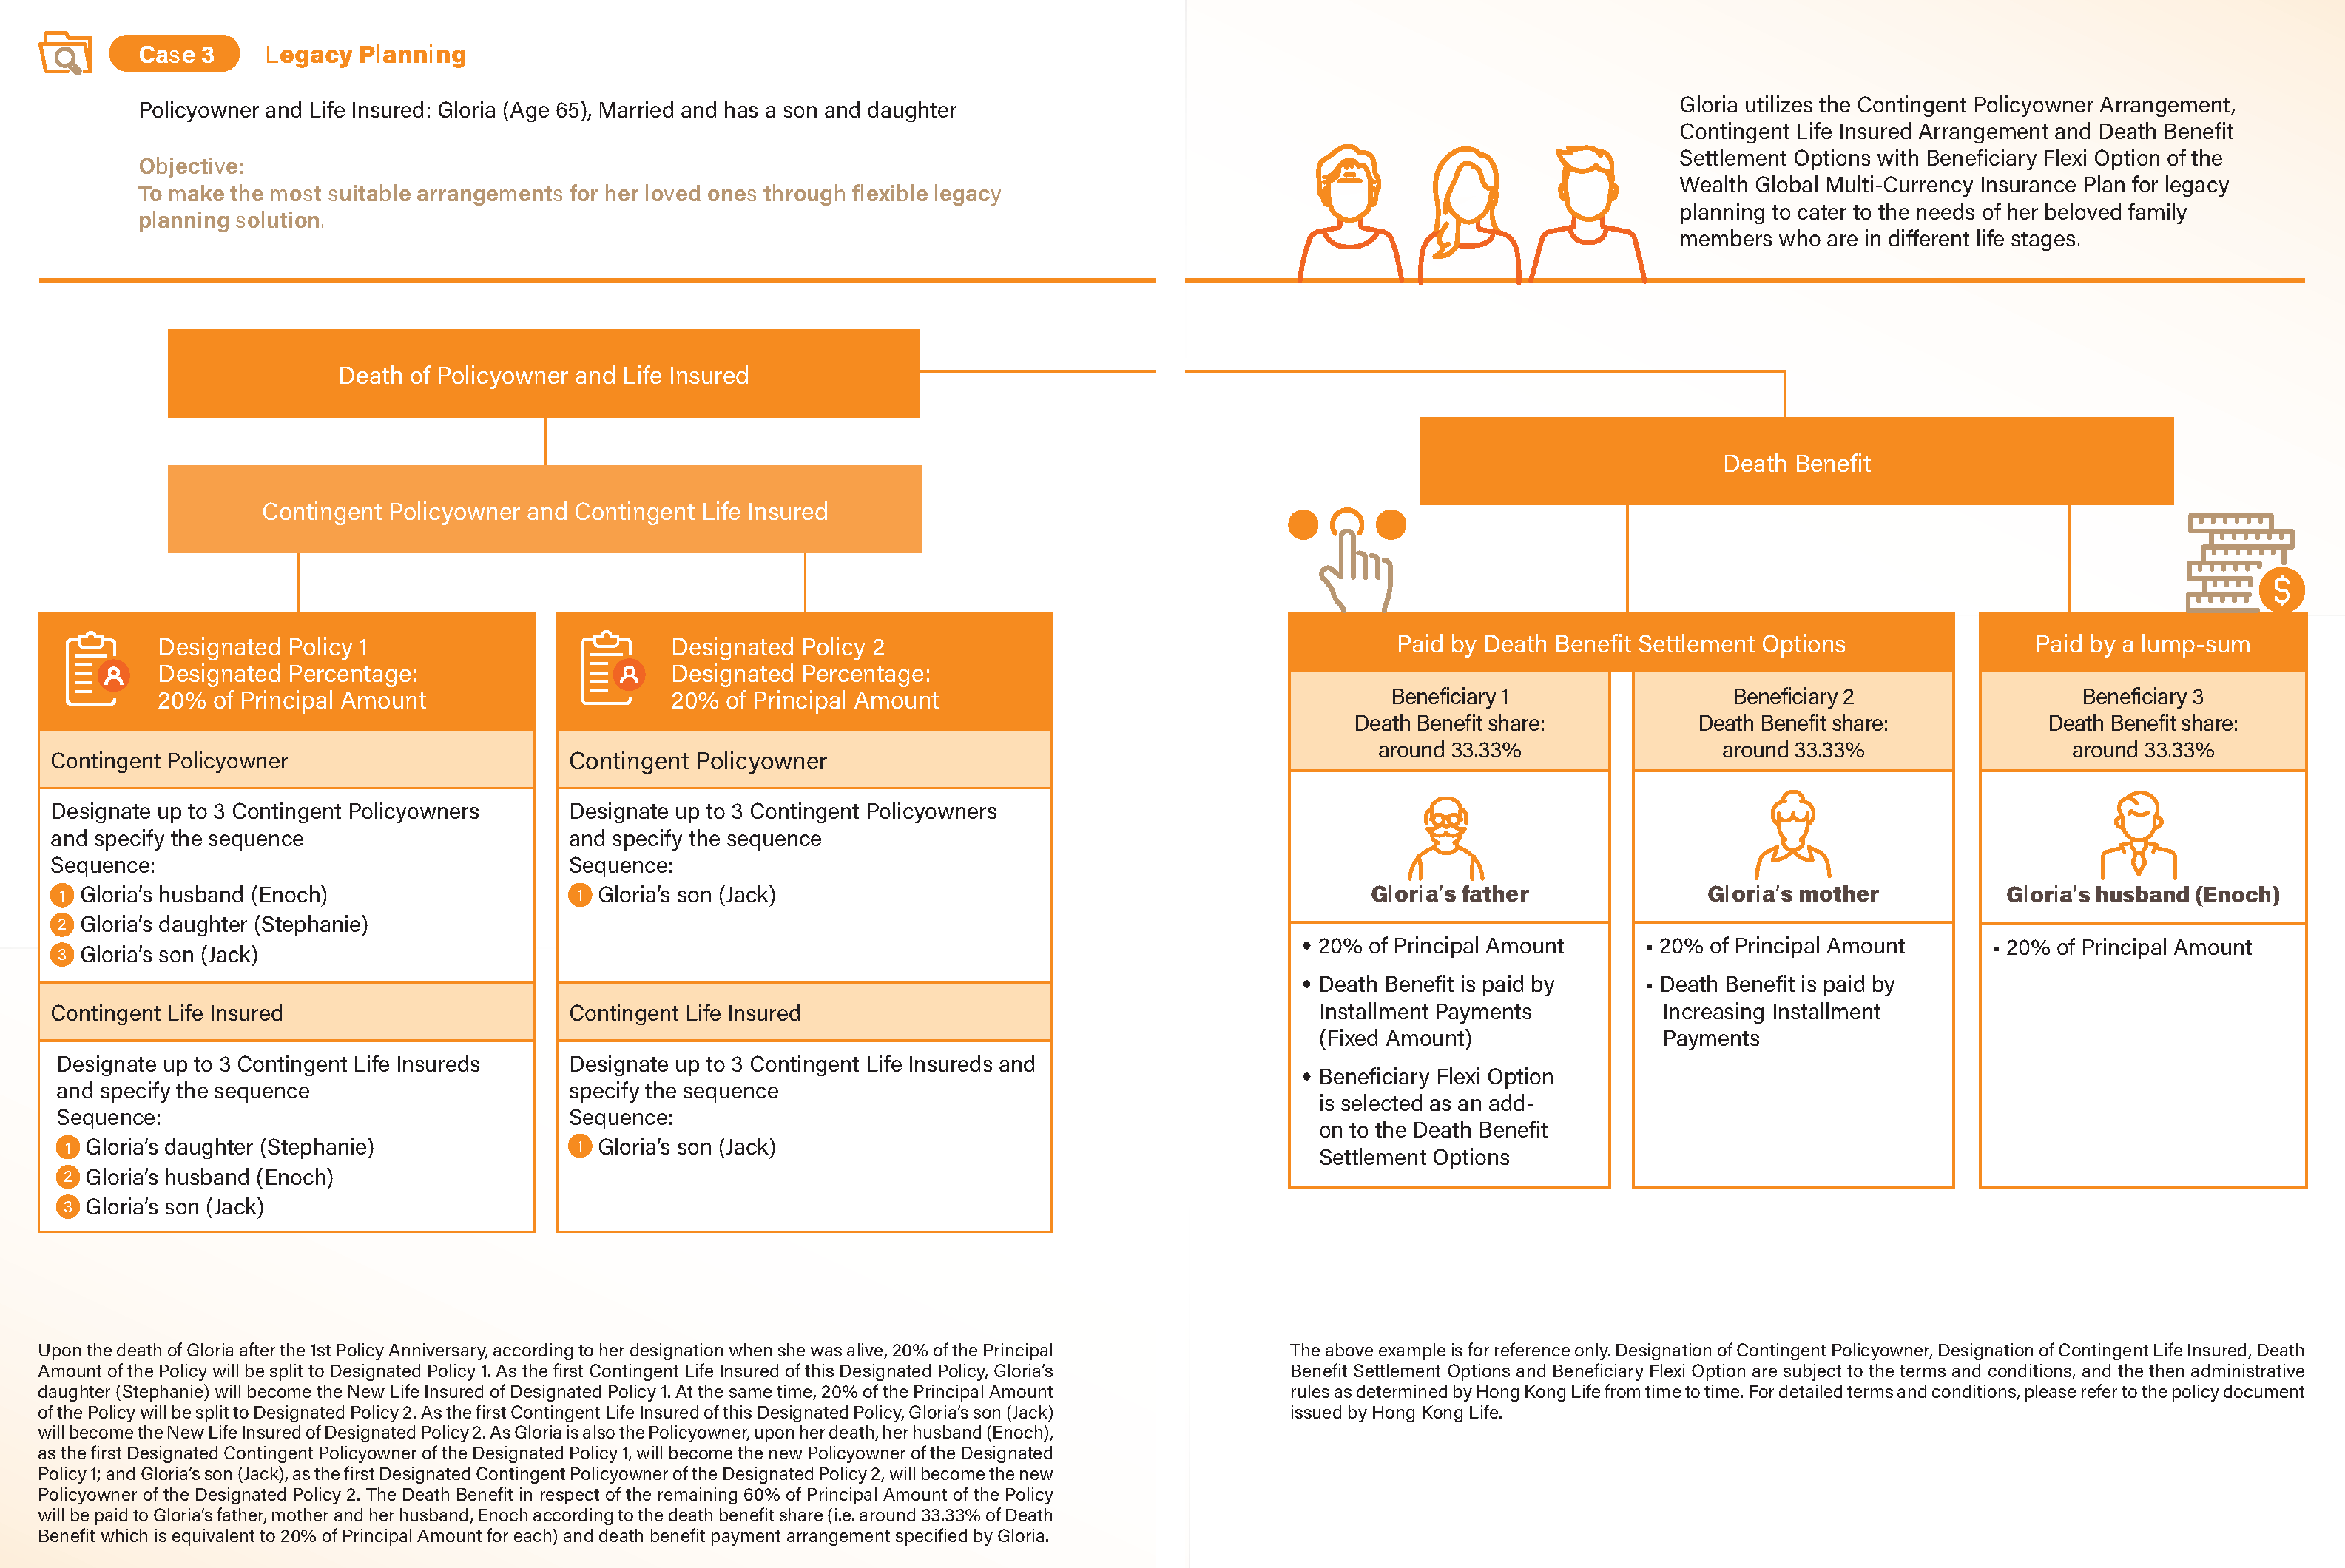
To safeguard the wealth management planning, during the lifetime of the Life Insured and while the Plan is in force, the Policyowner can designate up to 3 Contingent Policyowner(s) and designate the sequence of Contingent Policyowner to become the new Policyowner of the Policy in the event of death of the Policyowner. The ownership of the Policy will be transferred to the Contingent Policyowner according to the specified sequence in the event of death of the Policyowner. If the Policyowner requests to designate a split of the Policy under Contingent Life Insured arrangement by allocating a designated portion of the Principal Amount6 of the Policy to multiple separate new policy(ies) ("Designated Policy(ies)") in the event of death of the Life Insured, for each Designated Policy, the Policyowner can designate up to 3 Contingent Policyowner(s) and designate the sequence of Contingent Policyowner(s) to become the new Policyowner of such Designated Policy in the event of death of the Policyowner.
In the event of the death of the Policyowner, the Contingent Policyowner of first in sequence will become the new Policyowner. If the Contingent Policyowner of first in sequence cannot become the new Policyowner, the Contingent Policyowner of second in sequence will be arranged to become the new Policyowner, and so on.
- Interim Policyowner Arrangement11
Through the Interim Policyowner Arrangement11, the Policyowner can designate a Contingent Policyowner, as well as another interim policyowner (Aged 18 or above). In the event of death of the Policyowner, the interim policyowner may manage the Policy using his/her designated policy administration rights until the Contingent Policyowner reaches a designated age or the designated date as determined by the Policyowner to then take over the ownership rights of the Policy.
- Contingent Life Insured Arrangement12
To lower the impact of any sudden events and ensure that your wealth can be passed on through generations according to your wishes, the Policyowner can designate up to 3 Contingent Life Insured(s) while the Plan is in force and the Life Insured is alive and designate the sequence of Contingent Life Insured(s) to become the new Life Insured of the Policy in the event of death of the Life Insured. Policyowner may also request to designate a split of the Policy by allocating a designated portion of the Principal Amount6 of the Policy to multiple separate new policy(ies). For each Designated Policy, the Policyowner can designate up to 3 Contingent Life Insured(s) and designate the sequence of Contingent Life Insured(s) to become the new Life Insured of such Designated Policy in the event of death of the Life Insured. The designated portion of the Principal Amount6 to be allocated from the Policy to each of Designated Policy must be specified by the Policyowner and is subject to the minimum amount or any other relevant requirements as determined by Hong Kong Life from time to time.
In the event of the death of the Life Insured on or after the 1st Policy Anniversary, the Contingent Life Insured of first in sequence will become the new Life Insured. If the Contingent Life Insured of first in sequence cannot become the new Life Insured, the Contingent Life Insured of second in sequence will be arranged to become the new Life Insured, and so on. This ensures the Policy continues and avoids termination in the sudden event of the death of the Life Insured.
Extensive Life Protection for Peace of Mind
- Life Protection
When the Life Insured dies and provided that there is no named and surviving Contingent Life Insured who will become the new Life Insured, the Total Death Benefit will be paid to the Beneficiary as below:
| Policy Year | Total Death Benefit | |
|---|---|---|
|
1 - 2 |
100% of Total Premiums Paid13 | less Indebtedness (if any) |
|
3 and onwards |
101% of Total Premiums Paid13 OR 100% of Guaranteed Cash Value as at the date of death of the Life Insured plus Terminal Dividend (non-guaranteed)3 |
plus Accumulated Dividends and Interest (non-guaranteed)3,9 (if any), less Indebtedness (if any) |
In case of Partial Surrender4, the Principal Amount6 shall be reduced proportionally based on the percentage of Guaranteed Cash Value and Terminal Dividend (non-guaranteed)3(if any) being withdrawn for the Partial Surrender4. Upon the reduction of Principal Amount6, the Guaranteed Cash Value, Annual Dividend (non-guaranteed)3(if any), Terminal Dividend(non-guaranteed)3(if any), premium (if any) and Total Premiums Paid13 of the Plan shall be reduced proportionately. Total Death Benefit shall also be adjusted accordingly.
- Flexible Death Benefit Settlement Options14 (with Beneficiary Flexi Option15)
The Plan provides flexible Death Benefit Settlement Options14. Instead of receiving the Death Benefit in a lump sum payment, Policyowner can designate one of the following settlement options while the Plan is in force and the Life Insured is alive to settle the Death Benefit to the Beneficiary. If there is more than one Beneficiary named in the Policy, different settlement options can be specified for different Beneficiaries. For more flexibility of estate planning, the date to start the first installment payment can also be chosen.
- Installment Payments (Fixed Amount)
Death Benefit will be paid in fixed amount at regular intervals (monthly, quarterly, semi-annually or annually), and the date of first installment payment can also be specified. - Installment Payments (Fixed Period)
Death Benefit will be paid in installments (monthly, quarterly, semi-annually or annually) for an agreed fixed payment period, and the date of first installment payment can also be specified. - Partial Installment Payments (Fixed Amount)
A designated percentage of Death Benefit will be paid in a lump sum. The unpaid balance of Death Benefit will be paid in fixed amount at regular intervals (monthly, quarterly, semi-annually or annually), and the date of first installment payment can also be specified. - Partial Installment Payments (Fixed Period)
A designated percentage of Death Benefit will be paid in a lump sum. The unpaid balance of Death Benefit to be paid in installments (monthly, quarterly, semi-annually or annually) for an agreed fixed payment period, and the date of first installment payment can also be specified. - Partial Installment Payments until the Designated Age of the Beneficiary
Death Benefit will be paid in fixed amount at regular intervals (monthly, quarterly, semi-annually or annually) before the Designated Age of the Beneficiary, and the date of first installment payment can also be specified. The unpaid balance of Death Benefit (if any) will be paid in a lump sum at the Designated Age of the Beneficiary. - Increasing Installment Payments
Death Benefit will be paid by increasing installments (monthly, quarterly, semi-annually or annually), and the date of first installment payment can also be specified. Death Benefit will be paid in a specified amount for the first installment. The subsequent installments will be increased by 3% each year starting from the second year until Death Benefit is fully settled.
Beneficiary Flexi Option15
If the Policyowner has opted for the Death Benefit Settlement Options above, he/she can apply for the Beneficiary Flexi Option15.
Under the Beneficiary Flexi Option15, in the event that the Beneficiary has attained the Age of 18 or above and is diagnosed with a Specified Illness16 or sustains an injury resulting in Accidental Dismemberment17 within 365 days from the date of injury during the period the relevant Death Benefit becomes payable under the Death Benefit Settlement Option for such Beneficiary, Hong Kong Life will pay to the Beneficiary in a lump sum any unpaid balance of the relevant Death Benefit, providing the Beneficiary with immediate financial aid.
Other Benefit
- Incapacity Benefit5
In the face of life uncertainties, apart from planning for your loved one, you also need to keep yourself in mind in order to ensure that everything is taken care of. The Plan provides Incapacity Benefit5, which the Policyowner can designate one person ("Incapacity Benefit Recipient") to receive the Incapacity Benefit5 and the percentage ("Incapacity Benefit Percentage") for the amount of Incapacity Benefit5 while the Plan is in force and the Life Insured is alive. In the event that the Policyowner is diagnosed with a Covered Illness while the Policy is in force, the Incapacity Benefit5 will be paid to the Incapacity Benefit Recipient during the lifetime of the Policyowner. This provides immediate financial support to your family to cope with medical and rehabilitation expenses. Incapacity Benefit5 can only be paid once for each Policy.
Fixed Premium for Your Better Planning
The premium will remain unchanged throughout the Premium Payment Term1, allowing you to better plan your future.
Simple Application
The Life Insured will not have to go through any medical examination, up to a certain Principal Amount6 subject to the prevailing administrative rules as determined by Hong Kong Life.
| Premium Payment Term1 | 2 Years | 5 Years |
|---|---|---|
| Issue Age* | Age 0 (15 days after birth) to 80 | Age 0 (15 days after birth) to 75 |
| Policy Currency | HKD / USD / RMB | |
| Benefit Term | Until age 130 of the Life Insured / New Life Insured | |
| Minimum Principal Amount6 | HKD240,000 / USD30,000 / RMB216,000 | |
| Premium Payment Mode | Annual / Monthly+ | |
*Age means age of the Life Insured at the last birthday
+Monthly mode is only applicable to HKD and USD policies


- The Policy will be terminated if the Policyowner cannot settle the premium payment before the end of the Grace Period during the Premium Payment Term, subject to the Automatic Premium Loan (Automatic Premium Loan is only applicable to 5-Year Premium Payment Term Policies), Non-forfeiture Option and other relevant provisions of the Policy. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life. If the Policy is terminated before the Policy Maturity, the Total Surrender Value (if applicable) received by the Policyowner may be less than the Total Premiums Paid.
- Change of Life Insured is subject to the administrative rules and requirements as determined by Hong Kong Life from time to time, and the rights of any named assignee. The Principal Amount, Guaranteed Cash Value, Annual Dividend (if any), Terminal Dividend (if any), premium (if any), Total Premiums Paid, Policy Date, Issue Date, Premium Payment Term, Policy Years and Indebtedness (if any) will remain unchanged on the date of endorsement unless the change of Life Insured may trigger consequential adjustment in the Principal Amount and/or other policy value(s). The Maturity Date of the Policy will change based on the Age of the New Life Insured. At the time Hong Kong Life receives the written request, the proposed New Life Insured's age must fulfill the issue age requirement and must not be older than the Initial Life Insured. Also, evidence of insurability including the insurable interest for the proposed New Life Insured shall be submitted. In addition, the New Life Insured and the Previous Life Insured must be alive on the date of endorsement. All Supplementary Benefit(s) (if any) for the Previous Life Insured will be terminated automatically on the date of endorsement and no unearned premium shall be refunded. The relevant Supplementary Benefit(s) can be applied in respect of the New Life Insured subject to the underwriting and administrative rules and requirements as determined by Hong Kong Life from time to time. Any Contingent Policyowner and Contingent Life Insured of the Policy as previously recorded and endorsed by Hong Kong Life will be automatically cancelled and removed once the application for the change of Life Insured is accepted and approved by Hong Kong Life. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life.
- Annual Dividend, the annual interest accumulation rate and Terminal Dividend are not guaranteed and may be changed from time to time. Past performance is not indicative of future performance. The actual amount payable may be higher or lower than those illustrated in the Insurance Proposal. Hong Kong Life reserves the right to change them from time to time. The Annual Dividend and/or interest withdrawn will no longer be accumulated as part of the Total Surrender Value and the Total Death Benefit of the Policy. The Total Surrender Value and the Total Death Benefit of the Policy will be reduced accordingly.
- If Partial Surrender is exercised in the Policy, the Principal Amount shall be reduced proportionally based on the percentage of Guaranteed Cash Value and Terminal Dividend (if any) being withdrawn for the Partial Surrender. Upon the reduction of Principal Amount, the Guaranteed Cash Value, Annual Dividend (if any), Terminal Dividend (if any), premium (if any) and Total Premiums Paid of the Plan shall be reduced proportionately. Death Benefit, Maturity Benefit, and Incapacity Benefit (if any) shall also be adjusted accordingly. Partial Surrender is subject to the terms and conditions, and the then administrative rules as determined by Hong Kong Life from time to time. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life.
- Incapacity Benefit is subject to the applicable laws and regulations, administrative rules and requirements as determined by Hong Kong Life from time to time. The Incapacity Benefit Percentage is subject to the minimum amount or any other relevant requirements as determined by Hong Kong Life from time to time. The proposed Incapacity Benefit Recipient must be aged 18 or above at the time of submission and evidence of insurable interest must be submitted. Hong Kong Life reserves the right not to accept any application for the designation of Incapacity Benefit Recipient and to suspend and/or terminate the offering of Incapacity Benefit from time to time. If the Policyowner is diagnosed of a Covered Illness including Apallic Syndrome, Coma, Loss of Independent Existence, Major Head Trauma, Mental Incapacity, Paralysis and Terminal Illness while the Policy is in force, subject to the provisions, conditions and limitations, Hong Kong Life will pay to the Incapacity Benefit Recipient an Incapacity Benefit as follows:
i. If the Incapacity Benefit Percentage is 100%, the Policy will be fully surrendered. The full surrender value which is equal to (i) the Guaranteed Cash Value, plus (ii) Accumulated Dividends and Interest (if any) and (iii) Terminal Dividend (if any), less (iv) Indebtedness (if any) will be payable to the Incapacity Benefit Recipient. Once fully surrendered, the Policy shall terminate.
ii. If the Incapacity Benefit Percentage is less than 100%, the amount of Incapacity Benefit equals to (i) the sum of Guaranteed Cash Value, Accumulated Dividends and Interest (if any) and Terminal Dividend (if any) multiplied by the Incapacity Benefit Percentage, less (ii) Indebtedness (if any). Any Accumulated Dividends and Interest will be withdrawn first for the payment of Incapacity Benefit. If Accumulated Dividends and Interest is not sufficient to cover the amount of Incapacity Benefit, Partial Surrender will be triggered automatically. Part of Guaranteed Cash Value and Terminal Dividend (if any) will be withdrawn. The Principal Amount shall be reduced proportionally based on the percentage of Guaranteed Cash Value and Terminal Dividend (if any) being withdrawn for the automatic Partial Surrender. Upon the reduction of Principal Amount, the Guaranteed Cash Value, Annual Dividend (if any), Terminal Dividend (if any), premium (if any) and Total Premiums Paid of the Plan shall be reduced proportionately. Death Benefit and Maturity Benefit shall also be adjusted accordingly. Since the Principal Amount of the Plan cannot be less than the required minimum amount as determined by Hong Kong Life after automatic Partial Surrender. The actual amount of Incapacity Benefit payment may be less than the amount payable as mentioned above. Payment made shall constitute a full discharge of Hong Kong Life's obligations in respect of such Incapacity Benefit, and Hong Kong Life shall not be liable to the Policyowner and any other persons (including, if applicable, the estate of the Policyowner and his/her personal representatives, Contingent Policyowner and Beneficiary) in respect of any payment of Incapacity Benefit.
The Incapacity Benefit is payable in the event that the Policyowner is diagnosed of a Covered Illness, including physical or mental incapacity, and therefore extra care should be taken in giving instruction in respect of such Incapacity Benefit. The Policyowner should ensure that he/she has the mental capacity when giving such instructions, otherwise such instructions may be subject to challenge or become void. To better protect the Policyowner's rights, the application of the designation of the Incapacity Benefit Recipient should be signed by the Policyowner in the witness of an independent third party. In case of a dispute, Hong Kong Life reserves the right to withhold the payment of Incapacity Benefit until such dispute is resolved. For definition of Covered Illness, detailed terms and conditions of Incapacity Benefit, please refer to the policy document issued by Hong Kong Life. - Principal Amount is used to calculate Initial Premium, any subsequent premium, benefits and policy values (if any) of the respective Basic Plan and any Supplementary Benefit (if applicable). Any subsequent change of the Principal Amount will result in corresponding change in premium, benefits and policy values (if any) of the respective Basic Plan and any Supplementary Benefit (if applicable). The Principal Amount does not represent the amount of death benefit of the respective Basic Plan and any Supplementary Benefit (if applicable).
- Change of Policy Currency Option is subject to the applicable laws and regulations, administrative rules and requirements as determined by Hong Kong Life from time to time. When applying for the change of policy currency, all of the following conditions must be met:
i. The New Policy Currency shall be a different currency from the current Policy Currency of the Policy at the time of application and the New Policy Currency will not be available for selection if it is demonetized by the issuance country or region at the time of change of policy currency; and
ii. The Policyowner can apply for change of policy currency only 1 time every Policy Year; and
iii. There is no outstanding Indebtedness and all premiums due have been paid under the Policy; and
iv. No claims are currently being processed or have been made under the Policy; and
v. The Principal Amount of the Basic Plan under the New Policy must not less than the minimum requirement as determined by Hong Kong Life from time to time; and
vi. The application for change of policy currency cannot be withdrawn, amended or reverted once made.
Once the application for change of policy currency is accepted and approved by Hong Kong Life, a New Policy denominated in the New Policy Currency will replace the Policy, subject to the following terms and conditions:
i. Any request for the change of policy currency endorsed by Hong Kong Life will take effect on the date of endorsement which will be the Policy Monthiversary following the approval of the change of policy currency or as soon as practicable at a time determined by Hong Kong Life.
ii. The Basic Plan under the New Policy may or may not be the same as the Basic Plan under the Policy, subject to the eligible Basic Plan offered by Hong Kong Life at its discretion from time to time. Plan features, benefits and policy terms of the Basic Plan under the New Policy may be different from the Basic Plan of the Policy.
iii. There is no cooling-off period for the New Policy.
iv. Policy Date, Issue Date, Premium Payment Term, Maturity Date and Policy Years of the New Policy shall be the same as the Policy upon the effect of the change of policy currency.
v. Policy values under the Policy, including the Guaranteed Cash Value, Annual Dividend (if any), Terminal Dividend (if any), premium (if any) and Total Premiums Paid shall be converted to the New Policy Currency under the New Policy. Hong Kong Life shall determine and adjust (either increase or decrease) at its sole discretion the current and future policy values, including but not limited to the Principal Amount, Guaranteed Cash Value, Annual Dividend (if any), Terminal Dividend (if any), premium (if any) and Total Premiums Paid for the New Policy, based on factors including but not limited to the prevailing market-based currency exchange rate as determined by Hong Kong Life from time to time, the investment yield and asset values of the existing and new underlying portfolio of assets, and/or the transactions from the existing assets to new assets. Upon the adjustment of the policy values, Death Benefit, Maturity Benefit and Incapacity Benefit (if any) shall also be adjusted accordingly.
vi. Any Death Benefit Settlement Options, Beneficiary Flexi Option, Contingent Policyowner, Contingent Life Insured, Beneficiary and Incapacity Benefit Recipient of the Policy as previously recorded and endorsed by Hong Kong Life will be applied to the New Policy unless otherwise specified.
vii. The Policy Currency of any Supplementary Benefit(s) attached to the Policy will be converted to the New Policy Currency, provided that such Supplementary Benefit(s) is offered under the New Policy and is available in the New Policy Currency. Without prejudice to the termination clause of the Supplementary Benefit(s) attached to the Policy, if such Supplementary Benefit(s) is not offered under the New Policy or is not available in the New Policy Currency, or if exercising change of policy currency option that would trigger the new coverage amount of such Supplementary Benefit(s) to be lower than the minimum amount or any other relevant requirements as determined by Hong Kong Life from time to time, such Supplementary Benefit(s) will be terminate automatically on the effective date specified in the of new policy document.
Upon the application for change of policy currency is accepted and approved by Hong Kong Life, a new set of policy document specifying the date of endorsement, plan features, benefits and policy terms will be issued for the New Policy and the Policy shall automatically terminate. Hong Kong Life reserves the right not to accept any application of change of policy currency and has the absolute discretion to determine the administrative rules and requirements in respect of change of policy currency from time to time. Hong Kong Life reserves the right to suspend and/or terminate the offering of change of policy currency option from time to time. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life. - Policy Split Option is subject to the rights of any named assignee, any applicable laws and regulations, administrative rules and requirements as determined by Hong Kong Life from time to time. The following conditions should also be met:
i. The Policyowner can apply for policy split only 1 time for every Policy Year; and
ii. There is no outstanding Indebtedness and all premiums due have been paid under the Policy; and
iii. No claims are currently being processed or have been made under the Policy; and
iv. The Principal Amount of the Policy and the Split Policy(ies) after policy split must not less than the minimum amount requirement as determined by Hong Kong Life from time to time; and
v. The application for policy split cannot be withdrawn, amended or reverted once made.
Once the application for policy split is accepted and approved by Hong Kong Life, new Split Policy(ies) and an endorsement of the Policy will be issued to the Policyowner and the policy split will be deemed to be effective as of the date such policy split is recorded during the lifetime of the Life Insured and endorsed by Hong Kong Life, it is subject to the following conditions and limitations:
i. Any request for the policy split endorsed by Hong Kong Life will take effect on the date of endorsement which will be the Policy Monthiversary following the approval of the policy split or as soon as practicable at a time determined by Hong Kong Life.
ii. There is no cooling-off period for the Split Policy(ies).
iii. Upon acceptance and approval by Hong Kong Life, the Principal Amount of the Policy will be transferred to the Split Policy(ies) in accordance with the designated portion of the policy split as specified by the Policyowner and the Principal Amount of the Policy will be reduced after transfer. Hong Kong Life will determine the respective new Principal Amount of the Policy after split and the Split Policy(ies).
iv. The Policy Currency, Policy Date, Issue Date, Premium Payment Term, Maturity Date and Policy Years of the Split Policy(ies) will be the same as the Policy. All Policy values under the Policy, including the Guaranteed Cash Value, Annual Dividend (if any), Terminal Dividend (if any), premium (if any) and Total Premiums Paid will be reduced and transferred to the Split Policy(ies) in accordance with the new Principal Amount for the Policy and Split Policy(ies) after policy split. The adjustment of policy values in the Policy and the Split Policy(ies) after policy split will become the basis for the calculation of Death Benefit, Maturity Benefit and Incapacity Benefit (if any) in the Policy and the Split Policy(ies).
v. All benefits, terms and conditions of the Policy will apply to the Split Policy(ies) unless otherwise specified.
vi. Any Death Benefit Settlement Options, Beneficiary Flexi Option, Contingent Policyowner, Contingent Life Insured, Beneficiary and Incapacity Benefit Recipient of the Policy as previously recorded and endorsed by Hong Kong Life will be kept under the Policy and applied to Split Policy(ies) unless otherwise specified.
vii. All Supplementary Benefit(s) attached to the Policy will remain in force. Without prejudice to the termination clause of the Supplementary Benefit(s) attached to the Policy, the Supplementary Benefit(s) shall be terminated automatically on the date of endorsement if there is a reduction of coverage amount of Supplementary Benefit(s) induced by the reduction of the Principal Amount of the Policy to be lower than the minimum amount or any other relevant requirements as determined by Hong Kong Life from time to time. Hong Kong Life reserves the right not to accept any application of policy split and has the absolute discretion to determine the administrative rules and requirements in respect of policy split from time to time.
Hong Kong Life reserves the right not to accept any application of policy split and has the absolute discretion to determine the administrative rules and requirements in respect of policy split from time to time. Hong Kong Life reserves the right to suspend and/or terminate the offering of policy split option from time to time. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life. - Accumulated Dividends and Interest means the aggregate of (1) the total amount of distributed Annual Dividend left with Hong Kong Life (if any); and (2) the total amount of interest accumulated on any distributed Annual Dividend left with Hong Kong Life.
- Designation of Contingent Policyowner is subject to the administrative rules and requirements as determined by Hong Kong Life from time to time, and the rights of any named assignee. The evidence of insurability including the existence of insurable interest for the proposed Contingent Policyowner(s) must be submitted. Upon the death of the Policyowner while the Policy is in force, the actual transfer of ownership of the Policy to the Contingent Policyowner shall be approved and becomes effective subject to Hong Kong Life's receipt of satisfactory proof of the Policyowner's death and any documents as requested, the relevant conditions and limitation, and the prevailing administrative rules and requirements of Hong Kong Life. Only one Contingent Policyowner is allowed to become the Policyowner of the Policy. All Supplementary Benefit(s) (if any) for the Policyowner of the Policy will be terminated automatically upon the date of death of the Policyowner and no unearned premium shall be refunded. The relevant Supplementary Benefit(s) can be applied for by the Contingent Policyowner, subject to the underwriting rules and requirements as determined by Hong Kong Life from time to time. Any Incapacity Benefit Recipient of the Policy as previously recorded and endorsed by Hong Kong Life will be automatically cancelled and removed upon the date of death of the Policyowner. For detailed terms and conditions, please refer to relevant form and the policy document issued by Hong Kong Life.
- The Interim Policyowner Arrangement is a Policy Administration Service and is not a product feature. Hong Kong Life reserves the right to withdraw the Interim Policyowner Arrangement or change the terms and conditions of the Interim Policyowner Arrangement and/or related requirements of the Interim Policyowner Arrangement at any time with sole and absolute discretion (such changes will be reflected on Hong Kong Life's prescribed form(s)), and without the obligation to provide any prior notice. For details of the Interim Policyowner Arrangement (including but not limited to the eligibility, risks and limitations), please refer to the service leaflet and form(s) of the Interim Policyowner Arrangement.
- Designation of Contingent Life Insured is subject to any applicable laws and regulations, administrative rules and requirements as determined by Hong Kong Life from time to time. The proposed Contingent Life Insured(s) must fulfill the issue age requirement and must not be older than the Initial Life Insured at the time Hong Kong Life receives the written request, and evidence of insurability including the existence of insurable interest for the proposed Contingent Life Insured(s) must be submitted. Upon the death of the Life Insured on or after the 1st Policy Anniversary while the Policy is in force, the actual change of Life Insured to the Contingent Life Insured shall be approved and becomes effective subject to Hong Kong Life's receipt of satisfactory proof of the Life Insured's death and any documents as requested, the relevant conditions and limitation, and the prevailing administrative rules and requirements of Hong Kong Life. Only one Contingent Life Insured is allowed to become the Life Insured of the Policy or each of Designated Policies (where applicable). If the Policyowner does not apply to allocate the Principal Amount of the Policy, the Policy shall continue to be in force when the Contingent Life Insured becomes the new Life Insured of the Policy. If the Policyowner apply to allocate the Principal Amount of the Policy to Designated Policy(ies), Designated Policy(ies) shall be issued in accordance with the designated portion as specified by the Policyowner and the Policy shall automatically terminate on the date of endorsement. The Contingent Life Insured(s) shall become the Life Insured of the newly issued Designated Policy(ies). The Policy Currency, Policy Date, Issue Date, Premium Payment Term and Policy Years of the Designated Policy(ies) will be the same as the Policy. The Maturity Date of the Policy or the Maturity Date of the Designated Policy(ies) (where applicable) shall be adjusted based on the Age of the new Life Insured. All policy values under the Designated Policy(ies), including the Guaranteed Cash Value, Annual Dividend (if any), Terminal Dividend (if any), premium (if any) and Total Premiums Paid shall also be adjusted in accordance to the designated portion as specified by the Policyowner. The adjustment of Principal Amount and policy values in the Designated Policy(ies) after exercising the designation of Contingent Life Insured option will become the basis for the calculation of Death Benefit, Maturity Benefit and Incapacity Benefit (if any) in the Designated Policy(ies). All Supplementary Benefit(s) (if any) of the Policy will be terminated automatically on the date of endorsement of this Policy and no unearned premium shall be refunded. The relevant Supplementary Benefit(s) can be applied in respect of the new Life Insured in the Policy or the Designated Policy(ies) (where applicable) subject to the underwriting and administrative rules and requirements as determined by Hong Kong Life from time to time. For detailed terms and conditions, please refer to relevant form and the policy document issued by Hong Kong Life.
- Total Premiums Paid means the total amount of due and payable premiums from the Policy Date up to the date of termination of the Plan, paid to the Plan and received by Hong Kong Life. Any payment in excess of such amount of due and payable premiums will not be included in the Total Premiums Paid.
- Death Benefit Settlement Options are only applicable in the event of the death of the Life Insured, and are subject to the administrative rules and requirements as determined by Hong Kong Life from time to time. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life.
- Beneficiary Flexi Option is subject to the administrative rules and requirements as determined by Hong Kong Life from time to time. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life.
- Specified Illness refers to the diagnosis of cancer, heart attack, kidney failure, stroke or terminal illness. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life.
- Accidental Dismemberment refers to the Beneficiary being diagnosed with dismemberment (i.e. Loss of one member or more members, paralysis or is permanently bedridden) after an Injury. For detailed terms and conditions, please refer to the policy document issued by Hong Kong Life.
- Policyowner may submit a written request in the form prescribed by Hong Kong Life at any time to change or remove an Incapacity Benefit Recipient and the Incapacity Benefit Percentage. Any change or removal of the Incapacity Benefit Recipient and the Incapacity Benefit Percentage must be accepted and approved by Hong Kong Life and shall only take effect on the date of endorsement.
- Any Incapacity Benefit Recipient of the Policy as previously recorded and endorsed by Hong Kong Life shall be automatically cancelled and removed and no Incapacity Benefit will be paid when any of the following occurs (including where the application for the payment of Incapacity Benefit has been made by the Incapacity Benefit Recipient but any of the following occurs before the date of approval of such claim):
a. the Policyowner designates a new Incapacity Benefit Recipient and it is accepted and approved by Hong Kong Life; or
b. the Policyowner is changed; or
c. the Policyowner dies and Hong Kong Life is notified of the same; or
d. the Life Insured dies and Hong Kong Life is notified of the same, subject to the "Designation of Contingent Life Insured" clause of the Plan; or
e. the Incapacity Benefit Recipient dies and Hong Kong Life is notified of the same. - Hong Kong Life reserves the right to remove the Incapacity Benefit Recipient or withhold the payment of Incapacity Benefit at any time without prior notice if the designation or change of Incapacity Benefit Recipient or the payment of Incapacity Benefit by Hong Kong Life conflicts with or appears to be in conflict with any applicable laws, regulations, court orders or its equivalent, or the interest of any other person.
- If (a) a committee or guardian is appointed under the Mental Health Ordinance (Cap. 136 of the Laws of Hong Kong) or a committee or guardian is appointed under similar laws in another jurisdiction; (b) Hong Kong Life is notified of a committee or guardianship order taking effect; (c) there is an enduring power of attorney covering the Policy; (d) Hong Kong Life is notified of an enduring power of attorney covering the Policy; or (e) the Policy has been assigned pursuant to the "Assignment" clause of the General Provisions of the Policy. Hong Kong Life will only make payment to the Incapacity Benefit Recipient under the Incapacity Benefit with the prior written consent of the committee or guardian (as applicable in (a) and (b)); and/or the attorney (as applicable in (c) and (d)); and/or the named assignee (as applicable in (e)), as the case may be.
- In case there is a dispute or in Hong Kong Life's reasonable belief, there may be a dispute between the Incapacity Benefit Recipient and any other person, including but not limited to the Policyowner, Policyowner's guardian or committee, attorney, Contingent Policyowner, Beneficiary(ies) or named assignee, or if Hong Kong Life may incur liability as a result of it making payment of Incapacity Benefit, Hong Kong Life reserves the right to withhold payment until such dispute or matter is resolved to its satisfaction.
- Hong Kong Life shall not be held responsible or liable if Hong Kong Life exercises its right of removal of the Incapacity Benefit Recipient or withholding the payment of Incapacity Benefit under the Incapacity Benefit clause.
For detailed terms and conditions of Incapacity Benefit, please refer to the policy document issued by Hong Kong Life.
-
Basic Plan
Risk
Exchange Rate Risk
You are subject to exchange rate risks for the Policy denominated in currencies other than the local currency. Exchange rates fluctuate from time to time. You may suffer a loss of your benefit values and the subsequent premium payments (if any) may be higher than your initial premium payment as a result of exchange rate fluctuations.
Currency Risk
RMB is currently not freely convertible and conversion of RMB through banks in Hong Kong is subject to the rules, guidelines, regulations and conditions from the banks and/or Relevant Authorities from time to time. The actual conversion arrangement will depend on the restrictions prevailing at the relevant time. As RMB is currently not freely convertible and is subject to exchange controls by the Chinese government, RMB currency conversion is subject to availability and Hong Kong Life may not have sufficient RMB at the relevant time.
Risk from Exercising Change of Policy Currency Option
In case the policy currency is changed under the Change of Policy Currency Option, the adjustments on policy value may be significant (either higher or lower) and the amount of policy value after exercising the Change of Policy Currency Option may be considerably less than the total amount of premiums paid. Any future premiums will be adjusted if the Change of Policy Currency Option is exercised within the Premium Payment Term. The approval of application of Change of Policy Currency Option and the availability of currency at the time of exercising the Change of Policy Currency Option will be subject to the prevailing laws and regulations. Hong Kong Life reserves the right not to accept any application of change of policy currency and has the absolute discretion to determine the administrative rules and requirements in respect of change of policy currency from time to time. Hong Kong Life reserves the right to suspend and/or terminate the offering of Change of Policy Currency Option from time to time.
Please note that the Basic Plan under the New Policy after change of policy currency may or may not be the same as the Basic Plan under the Policy, subject to the eligible Basic Plan offered by Hong Kong Life at its discretion from time to time. Plan features, benefits and policy terms of the Basic Plan under the New Policy may be different from the Basic Plan of the Policy. You shall not purchase this product solely for the Change of Policy Currency Option. Please carefully evaluate the difference between the Basic Plan under the Policy and the latest basic plan available for exchange when you exercise the Change of Policy Currency Option and consider whether the latest basic plan suits your needs.
Liquidity Risk / Long Term Commitment
The Plan is designed to be held until the Maturity / Expiry Date. If you partially surrender or terminate the Policy prior to the Maturity / Expiry Date, a loss of the premium paid may be resulted.
The premium of the Plan should be paid in full for the whole payment term. If you discontinue the payment, the Policy may lapse and a loss of the premium paid may be resulted.
Credit Risk of Issuer
The life insurance product is issued and underwritten by Hong Kong Life. The premium to be paid by you would become part of the assets of Hong Kong Life and that you and your Policy are subject to the credit risk of Hong Kong Life. In the worst case, you may lose all the premium paid and benefit amount.
Market Risk
The amount of dividends (if any) of the Plan depends principally on the factors including investment returns, claim payments, policy persistency rates, expenses (such as commission, underwriting, issuance, maintenance costs, and general overheads) and tax; while the annual interest accumulation rate principally depends on the factors including investment performance and market conditions. Hence the amount of dividends (if any) and annual interest accumulation rate are not guaranteed and may be changed over time. The actual dividends payable and annual interest accumulation rate may be higher or lower than the expected amount and value at the time when the Policy was issued.
Investment returns include investment income and changes in asset value of the underlying investment. Performance of the investment return is affected by interest earnings and other market risk factors including, but not limited to, interest rate or credit spread movements, credit events, price fluctuations in invested assets, and foreign exchange fluctuations.
Inflation Risk
When reviewing the values shown in the Insurance Proposal, please note that the cost of living in the future is likely to be higher than it is today due to inflation.
Important Policy Provisions
Suicide
If the Initial Life Insured commits suicide, while sane or insane, within one (1) year from the Issue Date or date of any reinstatement, whichever is later, the liability of Hong Kong Life shall be limited to a refund of paid premiums to the Beneficiary without interest less any existing Indebtedness. In the case of reinstatement, such refund of premium shall be calculated from the date of reinstatement.
Upon the change of the Life Insured(s), if the New Life Insured commit suicide, while sane or insane, within one (1) year from the date of endorsement or date of any reinstatement, whichever is the later, the liability of Hong Kong Life shall be limited to (i)(a) a refund of the Total Premiums Paid for the Plan (without interest) or (i)(b) the Guaranteed Cash Value and Terminal Dividend (if any), whichever is greater, plus (ii) Accumulated Dividends and Interest (if any), less (iv) Indebtedness (if any).
Incontestability
The validity of the Policy shall not be contestable except for (i) the non-payment of premiums, (ii) fraud or (iii) misstatement of age and/or sex as specified in the Misstatement of Age and/or Sex provisions, after it has been in force during the lifetime of the Initial Life Insured for two (2) years from the Issue Date or the date of any reinstatement, whichever is later. Premiums paid will not be refunded should the Policy be voided by Hong Kong Life.
Upon the change of the Life Insured, Hong Kong Life shall not contest the validity of the Policy after the change has been in force during the lifetime of the New Life Insured for two (2) years from the date of endorsement or date of any reinstatement, whichever is the latest, except for (i) the non-payment of premiums, (ii) fraud or (iii) misstatement of age and/or sex as specified in the Misstatement of Age and/or Sex provisions. Premiums paid will not be refunded should the Policy be voided by Hong Kong Life.
Automatic Termination
The Plan shall terminate automatically:
- upon the death of the Life Insured (provided that there is no named and surviving Contingent Life Insured who will become the new Life Insured pursuant to the "Designation of Contingent Life Insured" clause of the Plan); or
- if and when the Principal Amount of the Plan is allocated to Designated Policy(ies) pursuant to the "Designation of Contingent Life Insured" clause of the Plan; or
- if and when the Plan matures or is fully surrendered (including the full surrender triggered for the payment of Incapacity Benefit as specified in the Incapacity Benefit clause); or
- (Applicable to 2-Year Premium Payment Term Policies) if and when a premium remains unpaid at the end of the Grace Period as specified in the General Provisions of the Policy; or
- (Applicable to 5-Year Premium Payment Term Policies) if and when a premium remains unpaid at the end of the Grace Period as specified in the General Provisions of the Policy unless Automatic Premium Loan applies; or
- if and when the Indebtedness of the Policy equals to or exceeds the Guaranteed Cash Value; or
- (Applicable to 5-Year Premium Payment Term Policies) if and when the Guaranteed Cash Value less Indebtedness (if any) is less than the premium required to maintain the Policy up to the next premium due date as specified in the Automatic Premium Loan clause; or
- upon the Change of Policy Currency as specified in Change of Policy Currency Option clause.
Others
Insurance Costs
The Plan is an insurance plan with a savings element. Part of the premium pays for the insurance and related costs (if any).
Potential Fees and Charges
If the premium refund or the payout benefits is not in HKD, USD or RMB, the refund or the payout may only be made in the form of a telegraphic transfer and relevant fees and charges may apply. Such fees and charges will be deducted from the premium refund or the payout benefits by the sending bank and receiving bank. The amount of fees and charges will vary depending on the sending bank and receiving bank designated by the customer. For details of the fees and charges, you should refer to Hong Kong Life and the designated receiving bank.
Cooling-off Period
If you are not satisfied with your Policy, you have a right to cancel it within the cooling-off period and obtain a refund of any premium(s) and levy(ies) paid (in the original payment currency) to Hong Kong Life without any interest. A written notice signed by you should be received directly by Hong Kong Life Insurance Limited at 15/F Cosco Tower, 183 Queen's Road Central, Hong Kong within the cooling-off period (that is, the period of 21 calendar days immediately following either the day of delivery of the Policy or the Cooling-off Notice to you or your nominated representative (whichever is the earlier)). After the expiration of the cooling-off period, if you cancel the Policy before the end of the term, the projected Total Surrender Value (if applicable) may be less than the Total Premiums Paid.
Dividends
Hong Kong Life determines the amount of divisible surplus that will be distributed in the form of dividends. Dividends will be determined and distributed according to the Policy's terms and conditions and in compliance with the relevant legislative and regulatory requirements as well as relevant actuarial standards, whereas Terminal Dividend is available for certain types of policies and payable at the termination of the policies.
The amount of divisible surplus depends principally on the factors including investment returns, claim payments, policy persistency rates, expenses (such as commission, underwriting, issuance, maintenance costs, and general overheads) and tax. Hence the amount of dividends is not guaranteed and may be changed over time. The actual dividends payable may be higher or lower than the expected amount at the time when the policies were issued. The withdrawal of dividends will decrease the Total Surrender Value and Total Death Benefit of the Policy.
Investment returns include investment income and changes in asset value of the underlying investment. Performance of the investment return is affected by interest earnings and other market risk factors including, but not limited to, interest rate or credit spread movements, credit events, price fluctuations in invested assets, and foreign exchange fluctuations.
Partial Surrender
In case of Partial Surrender, the Guaranteed Cash Value and Terminal Dividend of the Policy will be decreased accordingly. This will also decrease the Principal Amount, Total Surrender Value, Total Death Benefit, Annual Dividend, premium, Total Premiums Paid and other benefits (if applicable) of the Policy.
Policy Loan
After the Plan has acquired a Guaranteed Cash Value and while the Policy is in force, the Policyowner may, upon the sole security and satisfactory assignment of the Policy to Hong Kong Life, apply for a Policy Loan from the Plan. Any loan on the Policy shall bear interest at a rate declared by Hong Kong Life from time to time. Interest on the loan shall accrue and compound daily from the date of loan. The Policy Loan Interest Rate is not guaranteed and will be changed from time to time. The loan and the interest accrued thereon shall constitute Indebtedness against the Policy. Interest shall be due on each Policy Anniversary subsequent to the date of loan. In the event that the Indebtedness of the Policy equals to or exceeds the Guaranteed Cash Value, the Policy will terminate. Any Policy Loan and accrued loan interest may reduce the Total Surrender Value and Total Death Benefit of the Policy.
The above information is for reference and is applicable within Hong Kong only. Unless otherwise specified, the defined terms used in the above information should have the same meanings as given to them in the policy document. The information of the above information does not contain the full terms of the policy document. For full terms and conditions, please refer to the policy document. If there is any conflict between the above information and the policy document, the latter shall prevail. The copy of the policy document is available upon request. Before applying for the insurance plan, you may refer to the contents and terms of the policy document. You may also seek independent and professional advice before making any decision.